The financial landscape is ever-evolving, and staying ahead of potential shifts is crucial for maintaining economic stability. As we look towards 2026, many financial experts are forecasting significant changes in interest rates. These anticipated 2026 interest rates hikes could have a profound impact on everything from mortgages and personal loans to business credit and investment returns. For individuals and businesses alike, understanding these potential changes and developing robust strategies for smart loan management is not just advisable, but essential. This comprehensive guide will delve into the expected trajectory of 2026 interest rates, explore the implications for various types of loans, and provide actionable strategies to help you navigate this future financial environment successfully.
Anúncios
The concept of interest rates, while seemingly complex, fundamentally represents the cost of borrowing money. When interest rates rise, borrowing becomes more expensive, which can affect consumer spending, business investment, and overall economic growth. Conversely, lower interest rates encourage borrowing and spending, stimulating economic activity. Central banks, like the Federal Reserve in the United States, use interest rates as a primary tool to manage inflation, employment, and economic stability. Their decisions are influenced by a myriad of factors, including inflation data, employment figures, geopolitical events, and global economic trends. Predicting the exact movement of 2026 interest rates is challenging, but by analyzing current economic indicators and expert forecasts, we can prepare for likely scenarios.
Understanding the Economic Context for 2026 Interest Rates
Before diving into specific strategies, it’s vital to grasp the broader economic context that will likely shape 2026 interest rates. Several key factors are currently at play and will continue to influence central bank decisions:
Inflationary Pressures
Inflation has been a dominant theme in recent years. While some of the immediate post-pandemic inflationary spikes have subsided, underlying pressures remain. Supply chain disruptions, geopolitical conflicts, and strong consumer demand can all contribute to persistent inflation. If inflation remains elevated or shows signs of resurgence, central banks may continue to use higher interest rates as a tool to cool down the economy. The goal is to bring inflation back to target levels (typically around 2%) without triggering a recession. Monitoring inflation reports will be critical in anticipating moves in 2026 interest rates.
Anúncios
Labor Market Dynamics
A strong labor market, characterized by low unemployment and rising wages, can also contribute to inflationary pressures. When people have jobs and higher incomes, they tend to spend more, which can drive up demand and prices. Central banks closely watch employment data, including job creation numbers, wage growth, and unemployment rates. A robust labor market might give central banks more leeway to maintain or even increase interest rates if inflation persists. Conversely, a weakening labor market could prompt them to pause or even cut rates to stimulate economic activity. The balance between full employment and price stability is a delicate one that will heavily influence 2026 interest rates.
Global Economic Outlook
No economy operates in isolation. Global economic conditions, including growth rates in major trading partners, international trade policies, and global financial stability, all play a role. For instance, a slowdown in major global economies could reduce demand for exports, impacting domestic growth and potentially influencing interest rate decisions. Geopolitical events, such as conflicts or trade disputes, can also introduce uncertainty and affect commodity prices, further complicating the inflation picture. Staying informed about global economic forecasts and political developments will provide a more complete picture of what to expect from 2026 interest rates.
Government Fiscal Policy
Government spending and taxation policies also have an impact. Large government deficits, financed by borrowing, can increase the overall demand for credit, potentially pushing up interest rates. Conversely, fiscal austerity measures might reduce demand. The interplay between monetary policy (central bank actions) and fiscal policy (government actions) is complex but crucial for understanding the broader economic environment that will shape 2026 interest rates.
Impact of Rising 2026 Interest Rates on Different Loan Types
The impact of rising 2026 interest rates will not be uniform across all types of loans. Understanding how different loans are affected is the first step in developing targeted management strategies.
Mortgages
For most homeowners, mortgages represent the largest debt. Rising interest rates primarily affect:
- Adjustable-Rate Mortgages (ARMs): If you have an ARM, your interest rate will periodically reset based on a benchmark rate. As 2026 interest rates climb, your monthly payments will increase, potentially significantly.
- New Mortgages: Those looking to purchase a home in 2026 will face higher borrowing costs, meaning higher monthly payments and potentially reduced purchasing power.
- Refinancing: The opportunity to refinance an existing mortgage at a lower rate becomes less attractive or even non-existent when rates are rising.
Preparing for higher 2026 interest rates means assessing your current mortgage terms and considering options like refinancing into a fixed-rate mortgage now, if current rates are still favorable compared to anticipated future rates.
Personal Loans and Lines of Credit
Many personal loans, especially those from online lenders or peer-to-peer platforms, often have variable interest rates. Similarly, personal lines of credit and home equity lines of credit (HELOCs) are typically tied to a benchmark rate like the prime rate. As 2026 interest rates increase, the cost of carrying these debts will rise, leading to higher minimum payments and a greater overall cost of borrowing. This can put a strain on monthly budgets if not properly managed.
Credit Card Debt
Credit card interest rates are almost universally variable and are directly linked to the prime rate. When the prime rate rises in response to central bank actions, credit card Annual Percentage Rates (APRs) typically follow suit within one or two billing cycles. This means that carrying a balance on your credit cards will become even more expensive. With 2026 interest rates potentially higher, prioritizing the payoff of high-interest credit card debt becomes even more critical.
Auto Loans
While many auto loans are fixed-rate, some can be variable. Even for fixed-rate loans, the initial rate offered will be higher if 2026 interest rates are elevated. This means that new car purchases will become more expensive, potentially impacting affordability. For those with existing auto loans, the impact is less direct unless the loan has a variable rate clause, which is less common but still exists.
Student Loans
Federal student loan interest rates are typically fixed for the life of the loan, set annually based on Treasury yields. However, private student loans can have variable rates. Borrowers with variable-rate private student loans will see their payments increase as 2026 interest rates rise. Even for federal loans, future borrowers in 2026 might face higher initial rates. Understanding the terms of your student loans is crucial for planning.
Business Loans and Commercial Credit
Businesses rely heavily on loans and lines of credit for operations, expansion, and inventory. Rising 2026 interest rates will increase the cost of doing business for many companies, particularly those with variable-rate loans or those planning significant capital expenditures. This can impact profitability, investment decisions, and even hiring plans. Small businesses, which often have less access to diverse financing options, can be particularly vulnerable to higher borrowing costs.
Proactive Strategies for Smart Loan Management Amidst 2026 Interest Rate Hikes
Given the potential for higher 2026 interest rates, taking proactive steps now can save you significant money and stress in the future. Here are comprehensive strategies for smart loan management:
1. Refinance Variable-Rate Debt to Fixed-Rate
If you have loans with variable interest rates, such as ARMs, HELOCs, or private student loans, now might be the opportune time to explore refinancing them into fixed-rate alternatives. Locking in a lower, stable interest rate before 2026 interest rates climb can protect you from future payment shocks. Evaluate the costs associated with refinancing (e.g., closing costs for mortgages) against the potential savings over the long term. This strategy is particularly powerful for large debts like mortgages.
2. Accelerate Debt Payoff
The most direct way to mitigate the impact of rising 2026 interest rates is to reduce your overall debt burden. Focus on paying down high-interest debts first, such as credit card balances and personal loans. Consider strategies like the debt avalanche method (paying off the highest interest rate debt first) or the debt snowball method (paying off the smallest balance first for psychological momentum). Every dollar you pay off now is a dollar that won’t accrue more interest when rates go up.
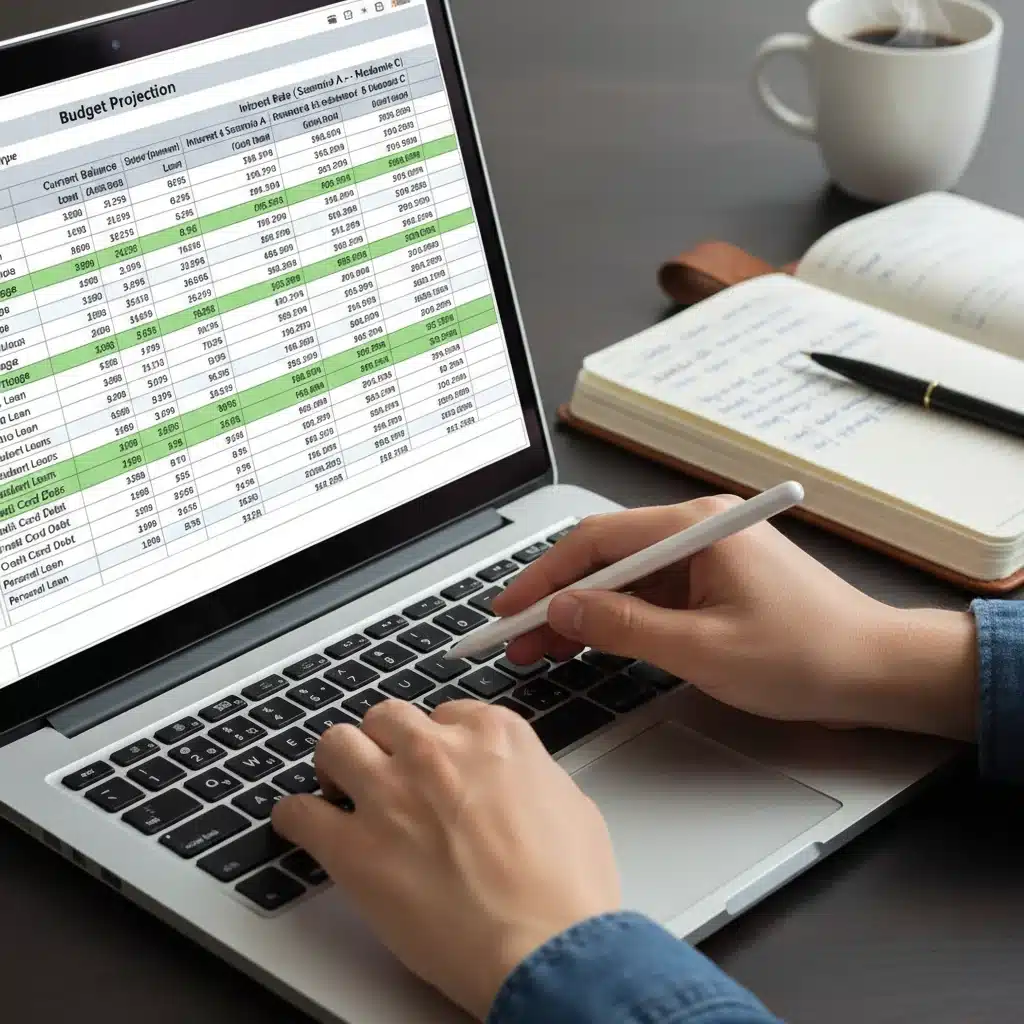
Even small extra payments can make a big difference over time. For example, if you have a mortgage, making one extra payment per year can significantly shorten the loan term and reduce the total interest paid. With 2026 interest rates on the horizon, this proactive approach is more valuable than ever.
3. Consolidate High-Interest Debt
Debt consolidation can be an effective strategy, especially for multiple high-interest debts like credit cards. By combining several debts into a single new loan, you might be able to secure a lower overall interest rate and simplify your payments. Options include:
- Personal Loans: Unsecured personal loans can be used to pay off credit card balances. Look for a fixed-rate personal loan with a lower APR than your credit cards.
- Balance Transfer Credit Cards: Some credit cards offer 0% APR on balance transfers for an introductory period. This can give you time to pay down debt without accruing interest, but be mindful of the balance transfer fees and ensure you can pay off the balance before the promotional period ends, especially with 2026 interest rates looming.
- Home Equity Loans/HELOCs: If you have substantial home equity, a home equity loan (fixed-rate) or HELOC (variable-rate) can offer lower interest rates than unsecured debt. However, remember that you are using your home as collateral, so this option carries more risk. Use a home equity loan to lock in a fixed rate if you choose this path.
Carefully evaluate the terms and conditions of any consolidation loan to ensure it genuinely saves you money, particularly with the backdrop of anticipated 2026 interest rates.
4. Build or Expand Your Emergency Fund
An adequate emergency fund is always important, but it becomes even more critical when interest rates are rising. Having a cash cushion can prevent you from needing to take on new, higher-interest debt in case of unexpected expenses (e.g., job loss, medical emergency, car repair). Aim for at least 3-6 months’ worth of essential living expenses. This financial buffer provides peace of mind and flexibility in a volatile interest rate environment, safeguarding you against the impact of higher 2026 interest rates on new borrowing.
5. Review and Adjust Your Budget
Now is an excellent time to conduct a thorough review of your budget. Identify areas where you can cut expenses to free up more cash for debt repayment or savings. Even small adjustments can add up. Consider tracking your spending meticulously for a month to identify hidden costs. A tighter budget allows you to be more agile in responding to changes in 2026 interest rates.
6. Negotiate with Lenders
If you’re struggling with existing debt or anticipating difficulties with rising payments due to 2026 interest rates, don’t hesitate to contact your lenders. They may be willing to work with you on modified payment plans, lower interest rates, or temporary deferments, especially if you have a good payment history. It’s always better to communicate proactively than to fall behind on payments.
7. Consider Financial Counseling
For those feeling overwhelmed by debt or unsure how to navigate the complexities of rising 2026 interest rates, seeking advice from a certified financial counselor can be invaluable. These professionals can help you create a personalized debt management plan, offer unbiased advice, and connect you with resources. Non-profit credit counseling agencies often offer free or low-cost services.
8. Diversify Investments (for Savers)
While this article focuses on loan management, it’s worth noting the flip side of rising interest rates: higher returns on savings. If 2026 interest rates climb, you may find better returns on savings accounts, certificates of deposit (CDs), and bonds. Review your investment portfolio to ensure it’s diversified and aligned with your risk tolerance and financial goals, potentially taking advantage of higher yielding, lower-risk options.
9. Stay Informed and Adapt
The economic landscape is dynamic. Continue to monitor economic news, central bank announcements, and expert forecasts regarding 2026 interest rates. Being informed allows you to adapt your strategies as new information becomes available. Flexibility and a willingness to adjust your financial plan will be key to successfully navigating the coming years.
Long-Term Financial Planning in a Higher Interest Rate Environment
Beyond immediate strategies for 2026 interest rates, it’s important to integrate these considerations into your long-term financial planning.
Future Borrowing Decisions
If you anticipate needing to take out new loans in 2026 or beyond (e.g., for a new home, car, or business expansion), factor higher interest rates into your affordability calculations. What might seem affordable today could be a stretch with increased borrowing costs. Pre-qualifying for loans now, if possible, might offer some protection against future rate hikes, though terms can still change.
Retirement Planning
Higher interest rates can influence retirement planning in several ways. On one hand, they can lead to better returns on fixed-income investments, which are often a component of retirement portfolios. On the other hand, if you plan to carry debt into retirement, the cost of that debt will be higher. Revisit your retirement projections and adjust your savings rate or investment strategy as needed to account for the impact of 2026 interest rates.
Business Strategy
For business owners, understanding the implications of 2026 interest rates is critical for strategic planning. This includes evaluating capital expenditure plans, managing cash flow, and assessing the cost of working capital. Businesses may need to explore alternative financing options or adjust pricing strategies to absorb higher borrowing costs. Diversifying funding sources and maintaining strong credit can also be crucial.
Furthermore, businesses should consider how higher interest rates might affect consumer demand for their products or services. If borrowing becomes more expensive for consumers, their discretionary spending might decrease, impacting sales. Proactive market analysis and scenario planning are essential.
Conclusion: Preparing for 2026 Interest Rates is Key
The anticipation of rising 2026 interest rates presents both challenges and opportunities. While higher borrowing costs can strain budgets and impact financial goals, proactive planning and strategic loan management can help mitigate these negative effects and even turn them into advantages. By understanding the economic forces at play, evaluating the impact on your specific debts, and implementing smart strategies like refinancing, accelerating debt payoff, and consolidating high-interest loans, you can build a more resilient financial future.
The time to prepare is now. Don’t wait until 2026 interest rates begin to climb before taking action. Review your financial situation, make informed decisions, and consider seeking professional advice to ensure you are well-positioned to navigate the evolving financial landscape. With careful planning and disciplined execution, you can protect your financial well-being and thrive even in a higher interest rate environment.