Raising Financially Resilient Children: 2026 Guide
In an ever-evolving global economy, equipping our children with robust financial literacy is no longer a luxury but a fundamental necessity. The world of 2026 demands more than just basic arithmetic; it calls for strategic thinking, prudent decision-making, and an understanding of complex financial instruments. This comprehensive guide, ‘The 2026 Guide to Raising Financially Resilient Children: From Allowance to Investment Accounts by Age 16,’ is designed to empower parents with the tools and knowledge to cultivate financially resilient children from an early age.
The journey to financial resilience begins long before a child earns their first paycheck. It starts with foundational concepts introduced through daily interactions, evolving into more sophisticated strategies as they mature. Our goal is to outline a clear, age-appropriate roadmap that ensures your child is not only comfortable with money but also capable of making informed financial decisions that will serve them well into adulthood. By focusing on practical, hands-on learning, we aim to demystify finance for both parents and children, turning what can often be an intimidating subject into an engaging and empowering experience.
The Foundation: Early Childhood (Ages 3-7) – Introducing Basic Money Concepts
The earliest years are crucial for laying the groundwork for financial understanding. At this stage, the focus is on introducing the concept of money as a medium of exchange and distinguishing between needs and wants. These initial lessons are best delivered through play and simple, real-world examples.
Understanding Money: Coins and Bills
Start by familiarizing children with different denominations of coins and bills. Use play money or real currency to teach them how to identify each, what they are called, and their relative values. Simple games like ‘store’ where they can ‘buy’ and ‘sell’ toys using play money can be incredibly effective. Explain that money isn’t infinite; it has to be earned.
Needs vs. Wants: The First Financial Lesson
This is perhaps one of the most critical lessons for developing financially resilient children. Engage your child in conversations about needs (food, shelter, clothing) versus wants (toys, candy, extra treats). When grocery shopping, point out essential items versus impulse buys. Ask them, ‘Do we need this, or do we want this?’ This simple question fosters critical thinking about spending decisions.
Introducing Allowance: Earning and Responsibility
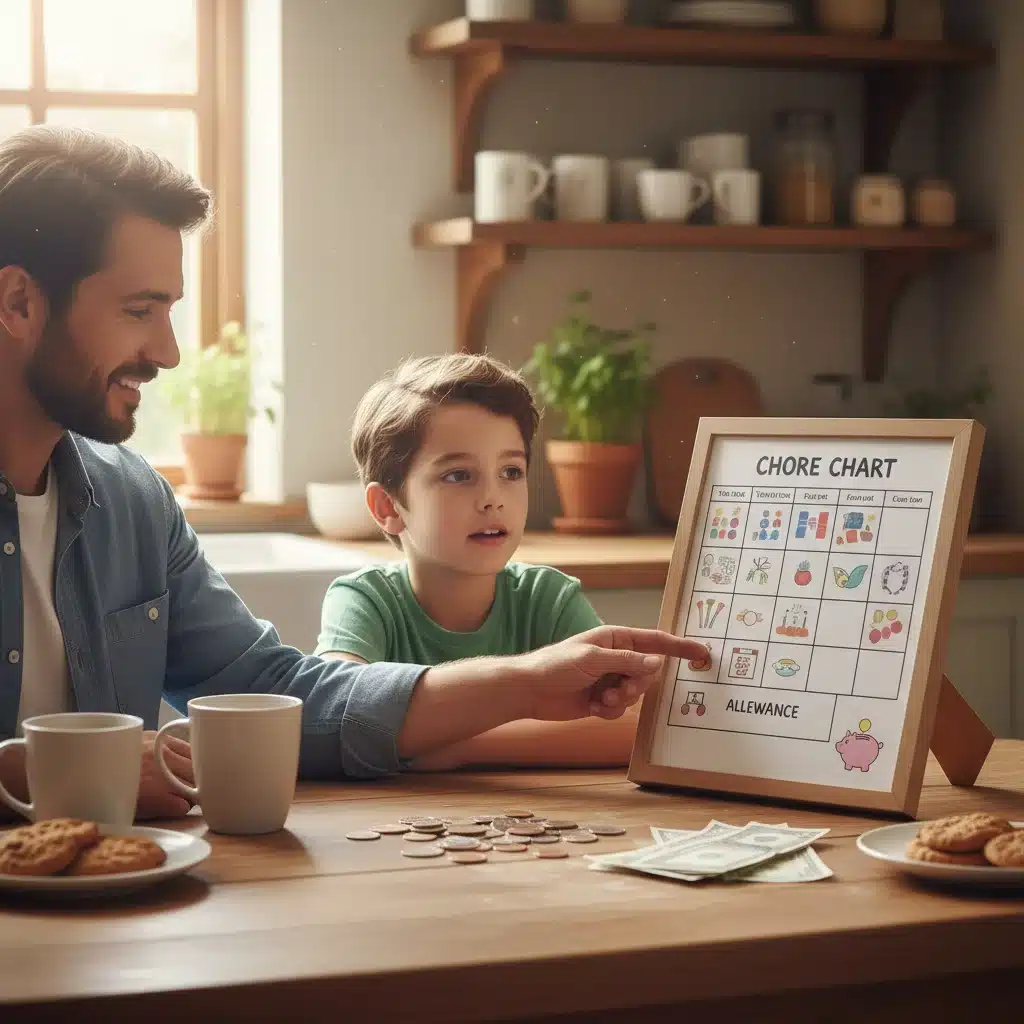
A small, consistent allowance can be introduced around age 5 or 6. The key is to link it to chores or responsibilities, teaching them that money is earned through effort. The amount doesn’t have to be large; it’s the principle that matters. For example, 50 cents or a dollar for making their bed or helping set the table. This early connection between work and reward is vital for raising financially resilient children.
The Three Jars: Save, Spend, Share
A classic yet effective method is to provide three clear jars labeled ‘Save,’ ‘Spend,’ and ‘Share.’ When they receive their allowance, help them divide it among the jars. The ‘Spend’ jar is for immediate gratification, the ‘Save’ jar for a larger, desired item, and the ‘Share’ jar for charity or helping others. This teaches them about delayed gratification, goal setting, and generosity – all hallmarks of financially resilient children.
Building Blocks: Middle Childhood (Ages 8-12) – Expanding Financial Horizons
As children grow, their cognitive abilities expand, allowing for more complex financial concepts. This stage focuses on understanding budgeting, the value of saving, and the basics of consumer choices.
Budgeting Basics: Tracking Income and Expenses
Move beyond the three jars to a simple ledger or a digital budgeting app designed for kids. Help them track their allowance and any money earned from chores or gifts. Encourage them to record how they spend their ‘Spend’ money. This visual representation helps them understand where their money goes and enables them to identify spending patterns. This is a crucial step in developing financially resilient children.
Setting Financial Goals: Short-Term and Long-Term
Encourage them to set both short-term (e.g., a new video game) and long-term (e.g., a bicycle or a special trip) savings goals. Break down larger goals into smaller, manageable steps. Discuss how much they need to save each week or month to reach their target. Celebrate milestones along the way to reinforce positive saving habits.
Understanding Advertising and Consumerism
The digital age bombards children with advertisements. Teach them to critically evaluate ads. Discuss how companies try to persuade people to buy things. Explain that just because something is advertised doesn’t mean it’s a good value or even necessary. This critical thinking skill is essential for financially resilient children who can resist impulse purchases.
The Concept of Interest: Money Earning Money
Introduce the idea that money can grow over time. While a traditional bank account might not offer significant interest for a child’s small savings, you can simulate it. For example, for every dollar they save towards a long-term goal, you might add an extra ten cents as ‘interest.’ This tangible experience helps them grasp the power of compounding.
Entrepreneurial Spirit: Earning Beyond Allowance
Encourage age-appropriate ways for them to earn extra money. This could be through lemonade stands, pet sitting, car washing, or helping neighbors with yard work. These experiences teach initiative, the value of hard work, and the satisfaction of earning their own money. These real-world applications are invaluable for nurturing financially resilient children.
Strategic Growth: Early Adolescence (Ages 13-16) – Investing and Future Planning
This stage is pivotal for transforming foundational knowledge into actionable financial strategies. By age 16, your child should have a solid understanding of basic investing principles and be capable of making independent, informed financial decisions.
Opening a Bank Account: Checking and Savings
Around age 13 or 14, help your child open their first bank account, typically a joint account with a parent. Teach them how to use a debit card responsibly, monitor their balance online, and understand bank statements. Explain fees, overdraft protection, and the importance of keeping their account secure. This practical experience is vital for developing financially resilient children.
Understanding Credit: The Basics and Dangers
Introduce the concept of credit – what it is, how it works, and its importance for future financial endeavors (e.g., buying a car, a home). Crucially, explain the dangers of debt, high-interest rates, and irresponsible credit use. Use analogies to make it relatable, like borrowing a toy and having to return it in good condition, plus an extra ‘thank you’ (interest).
The World of Investing: Simple Concepts
This is where many parents hesitate, but it’s crucial for raising truly financially resilient children. Start with simple explanations of what stocks, bonds, and mutual funds are. Use real-world examples of companies they recognize. Explain the concept of risk and reward – higher potential returns often come with higher risk.
Simulated Investing Games
Many online platforms offer simulated stock market games. Encourage your teenager to participate, allowing them to ‘invest’ a hypothetical sum of money and track its performance. This provides a risk-free environment to learn about market fluctuations and investment strategies.
Introduction to Index Funds and ETFs
For actual investing, introduce the idea of low-cost index funds or Exchange Traded Funds (ETFs) as a diversified and relatively safe entry point into the stock market. Explain that these funds hold a basket of many different stocks, reducing the risk compared to investing in a single company.
Opening an Investment Account by Age 16 (Custodial Account)
By age 16, consider opening a custodial investment account (UGMA/UTMA) in their name, with you as the custodian. Start with a small, manageable amount. This allows them to experience real-world investing, albeit with your guidance. Regularly review the portfolio with them, discussing performance and market news. This hands-on experience is paramount for fostering financially resilient children.
Career Exploration and Future Earnings Potential
Connect their interests and academic strengths to potential career paths and their associated earning potentials. Discuss the importance of education and skill development in increasing their future income. This helps them understand the long-term impact of their choices today on their financial future.
Philanthropy and Giving Back
Reinforce the ‘Share’ jar concept from earlier years by discussing philanthropy. Encourage them to research causes they care about and consider donating a portion of their earnings or savings. This teaches empathy, social responsibility, and the positive impact of money beyond personal gain.
Advanced Strategies: Beyond Age 16
While the focus of this guide is to reach a significant level of financial literacy by age 16, the journey doesn’t stop there. As your child approaches adulthood, these advanced strategies become increasingly relevant.
Understanding Taxes: Income and Investment Taxes
Introduce the basics of income tax, explaining why we pay taxes and how they fund public services. If they have an investment account, discuss capital gains taxes and how they apply to investment profits. This demystifies a complex but essential aspect of personal finance.
Retirement Planning: The Power of Compounding Early
It’s never too early to discuss retirement. Explain the concept of compound interest in the context of long-term savings for retirement. Show them how even small contributions made early can grow into substantial sums over decades. This long-term perspective is a hallmark of financially resilient children.
College Savings and Debt Management
If college is in their future, discuss the costs involved and different ways to fund it, including scholarships, grants, and student loans. Emphasize the importance of minimizing student loan debt and understanding repayment terms. This is a critical conversation for ensuring they start their independent adult lives on solid financial footing.
The Importance of an Emergency Fund
Teach them the necessity of having an emergency fund – a stash of savings to cover unexpected expenses. Explain that this fund provides a safety net and prevents them from going into debt when unforeseen circumstances arise. This is a core principle for building financially resilient children.
Parental Role: Leading by Example and Open Communication
Your role as a parent is the most influential factor in shaping your child’s financial habits and attitudes. Children are keen observers, and they often mirror the financial behaviors they witness at home.
Be a Role Model
Demonstrate good financial habits yourself. Let your children see you budgeting, saving, making thoughtful purchasing decisions, and even discussing financial challenges in a calm and constructive manner. Actions speak louder than words when it comes to teaching financially resilient children.
Foster Open Communication
Create an environment where money is not a taboo subject. Encourage questions and be transparent (within age-appropriate limits) about family finances. Discuss financial decisions, both big and small, and explain the reasoning behind them. This open dialogue builds trust and a deeper understanding.
Mistakes as Learning Opportunities
Children (and adults) will make financial mistakes. When your child overspends their allowance or makes a poor purchasing decision, use it as a teaching moment rather than a cause for punishment. Discuss what went wrong, what could have been done differently, and how to avoid similar errors in the future. These lessons are invaluable for developing financially resilient children.
Seek External Resources
Don’t feel you have to be a financial expert. Utilize books, online resources, educational games, and even financial advisors to supplement your teaching. Many banks and credit unions offer youth-focused financial education programs. Leveraging these resources can significantly enhance your child’s learning journey towards becoming financially resilient children.
Common Pitfalls to Avoid
Even with the best intentions, parents can inadvertently hinder their child’s financial development. Being aware of these common pitfalls can help you navigate the process more effectively.
Over-Sheltering from Financial Realities
While it’s important to protect children, completely shielding them from all financial discussions can leave them unprepared for the real world. Age-appropriate exposure to financial realities, such as the cost of living or the effort required to earn money, is crucial for fostering financially resilient children.
Inconsistency with Allowance/Chores
If allowance is tied to chores, be consistent. Inconsistent payment or allowing chores to go undone without consequence sends mixed messages and undermines the lesson of earning. Structure and predictability are key.
Bailing Them Out Too Often
While it’s hard to see your child struggle, constantly bailing them out when they overspend or make poor choices prevents them from learning from their mistakes. Allow them to experience the natural consequences of their financial decisions (within reason, of course) to build resilience.
Ignoring Financial Education Entirely
Perhaps the biggest pitfall is simply not engaging in financial education at all. Assuming schools or others will teach these vital skills can leave your child at a significant disadvantage. Active parental involvement is irreplaceable in raising financially resilient children.
Conclusion: The Lifelong Gift of Financial Resilience
Raising financially resilient children is one of the most profound and lasting gifts you can bestow upon them. It’s a continuous journey that requires patience, consistency, and a willingness to learn alongside your child. By implementing the strategies outlined in this 2026 guide, from the earliest lessons in allowance to the sophisticated world of investment accounts by age 16, you are not just teaching them about money; you are equipping them with critical life skills that foster independence, confidence, and security.
The goal is not to create child millionaires, but rather to nurture individuals who understand the value of hard work, the importance of saving, the power of smart investing, and the joy of giving back. These are the traits of truly financially resilient children who will be well-prepared to navigate the complexities of adulthood and build a secure and prosperous future for themselves and their communities. Start today, and watch your children grow into financially savvy, responsible adults ready to face whatever the future holds.