New Federal Student Loan Repayment Plans for 2026: What 3 Key Changes Mean for Your Budget
Anúncios
The landscape of federal student loan repayment is constantly evolving, and for millions of borrowers, 2026 is poised to bring significant shifts. As we approach these changes, understanding the nuances of the new federal student loan repayment plans becomes paramount. These aren’t just minor tweaks; they represent fundamental adjustments that could profoundly impact your financial future and monthly budget. Preparing now, by familiarizing yourself with the upcoming modifications, can make all the difference in navigating your student loan obligations effectively. The primary goal of these updates is often to make repayment more manageable for a broader range of borrowers, but the specifics can be complex and require careful attention. This comprehensive guide will delve into the three most critical changes expected in the Student Loan Repayment 2026 framework, offering insights into what they mean for you and actionable strategies to adapt.
For years, federal student loan programs have offered a lifeline to countless individuals pursuing higher education. However, the existing repayment structures, while varied, have often been criticized for their complexity and, at times, their inability to adequately address the financial realities of borrowers. The upcoming changes for Student Loan Repayment 2026 are largely a response to these concerns, aiming to streamline processes, reduce burdens for low-income earners, and potentially accelerate paths to loan forgiveness for certain groups. While the full details are still being solidified and may be subject to further legislative adjustments, the core proposals indicate a clear direction towards a more borrower-friendly system, albeit one that requires proactive engagement from those affected. It’s not just about knowing that changes are coming, but understanding the specific mechanisms of these changes and how they interact with your personal financial situation.
Many borrowers are already grappling with the complexities of existing income-driven repayment (IDR) plans, forbearance options, and the general weight of student debt. Adding new rules to the mix can feel overwhelming. However, by breaking down the key components of the Student Loan Repayment 2026 reforms, we can demystify the process and empower you to make informed decisions. This article will focus on the most impactful changes, offering practical advice and a clear roadmap to help you adjust your financial planning. Whether you’re a recent graduate, a seasoned professional with lingering debt, or someone anticipating future federal loans, these updates will likely touch your life. Let’s explore what’s on the horizon and how to prepare for the new era of federal student loan repayment.
Anúncios
Understanding the Current Landscape of Federal Student Loan Repayment
Before we dive into the specifics of Student Loan Repayment 2026, it’s crucial to have a foundational understanding of the current federal student loan repayment options. This context will help highlight the significance of the upcoming changes. Currently, federal student loan borrowers have several repayment plans available, each designed to cater to different financial situations. The most common include:
- Standard Repayment Plan: A fixed monthly payment over 10 years (or up to 30 years for consolidated loans). This plan typically results in the lowest total interest paid.
- Graduated Repayment Plan: Payments start low and gradually increase, usually every two years, over a 10-year period.
- Extended Repayment Plan: For borrowers with more than $30,000 in direct or FFEL loans, this plan offers fixed or graduated payments for up to 25 years.
- Income-Driven Repayment (IDR) Plans: These plans (REPAYE, PAYE, IBR, ICR) adjust your monthly payment based on your income and family size. Payments are typically a percentage (10-20%) of your discretionary income, and any remaining balance is forgiven after 20 or 25 years of payments.
The IDR plans have been particularly popular for borrowers struggling to afford their monthly payments under the standard plans. They offer a safety net, ensuring that payments are manageable, even if it means extending the repayment period and potentially paying more interest over time. However, IDR plans have also been criticized for their complexity, the need for annual recertification, and the fact that many borrowers still struggle to understand their benefits and drawbacks. The upcoming changes in Student Loan Repayment 2026 aim to simplify and improve upon these existing structures, particularly the IDR offerings, to provide more transparent and accessible relief to borrowers.
Another critical aspect of the current system is the concept of loan forgiveness. Public Service Loan Forgiveness (PSLF) allows eligible public sector employees to have their remaining loan balance forgiven after 120 qualifying monthly payments while working for a qualifying employer. While PSLF has been a game-changer for many, it has also faced challenges with eligibility criteria and processing. The Student Loan Repayment 2026 reforms may indirectly or directly influence the landscape of loan forgiveness, either by simplifying paths or by altering the underlying repayment structures that feed into forgiveness programs. Understanding your current plan and how it compares to the proposed changes is the first step toward smart financial planning.
Key Change 1: Streamlined Income-Driven Repayment (IDR) Plans
Perhaps the most significant overhaul for Student Loan Repayment 2026 will be the simplification and enhancement of income-driven repayment plans. Historically, the array of IDR options (REPAYE, PAYE, IBR, ICR) has been a source of confusion for borrowers, each with slightly different terms, eligibility requirements, and payment calculation methods. The goal of the upcoming changes is to consolidate and streamline these options, making it easier for borrowers to understand and choose the plan that best suits their needs.
What to Expect:
- Fewer IDR Options: Expect a reduction in the number of distinct IDR plans. The Department of Education has indicated a move towards a single, more universal IDR plan, or at least a significant consolidation. This aims to reduce complexity and ensure more borrowers can easily access income-based relief without getting lost in bureaucratic details.
- Revised Discretionary Income Calculation: A crucial element of IDR plans is how ‘discretionary income’ is defined. Currently, it’s generally the difference between your adjusted gross income (AGI) and 150% of the federal poverty guideline for your family size. The new rules for Student Loan Repayment 2026 are expected to adjust this calculation, potentially increasing the amount of income protected from repayment. This could mean lower monthly payments for many borrowers, especially those with lower incomes. For instance, if the protected income threshold is raised to 225% of the poverty line, a significant portion of income would be shielded, leading to a smaller ‘discretionary’ amount and thus a lower payment.
- Lower Payment Percentages: While current IDR plans typically require payments of 10-15% of discretionary income, there’s a strong indication that the new plan for Student Loan Repayment 2026 will feature even lower percentages, particularly for undergraduate loans. This could translate to substantial savings on monthly payments for many borrowers, freeing up more of their income for other essential expenses.
These changes are designed to address criticisms that existing IDR plans, while helpful, still left many borrowers with unmanageable payments or extended their repayment periods unnecessarily. By simplifying the choices and making payments more affordable, the new IDR framework aims to provide a more robust safety net for federal student loan borrowers. This is particularly beneficial for recent graduates or those in lower-paying fields who are just starting their careers. Understanding these changes is critical for anyone with federal student loans, as it could significantly alter your monthly financial obligations and long-term repayment strategy. Proactive engagement with your loan servicer once these changes are formally announced will be essential to ensure you are on the most advantageous plan.
Key Change 2: Accelerated Path to Loan Forgiveness
Beyond reducing monthly payments, another significant aspect of the Student Loan Repayment 2026 reforms focuses on accelerating the path to loan forgiveness for certain borrowers. Under current IDR plans, loan forgiveness typically occurs after 20 or 25 years of qualifying payments. This extended timeline has been a point of contention for many, as it can feel like a lifetime of debt. The upcoming changes aim to shorten this period, especially for those with smaller loan balances.
What to Expect:
- Shorter Forgiveness Timelines for Lower Balances: One of the most anticipated changes is the introduction of a shorter forgiveness timeline for borrowers with smaller original loan balances. For example, some proposals suggest that borrowers with original loan balances under $12,000 could see their remaining debt forgiven after just 10 years of payments. This is a radical departure from the current 20-25 year standard and could provide immense relief to a large segment of borrowers who took out smaller loans but have struggled with repayment.
- Counting More Payments Towards Forgiveness: The new rules for Student Loan Repayment 2026 are also expected to be more generous in what counts as a ‘qualifying payment’ towards forgiveness. This could include periods of forbearance or deferment, or even periods where borrowers were in default but subsequently rehabilitated their loans. The goal is to ensure that borrowers are not penalized for past financial hardships or administrative complexities, allowing them to reach forgiveness faster. This retroactive credit for certain payment periods could significantly reduce the time many borrowers have left until their debt is cleared.
- Automatic Enrollment and Recertification: While not directly related to the forgiveness timeline, proposals for automatic enrollment into the most beneficial IDR plan and streamlined annual recertification processes could indirectly accelerate forgiveness. By reducing administrative hurdles and ensuring borrowers are always on the optimal plan, fewer people will fall out of qualifying payment status, thus maintaining their progress towards forgiveness.
These accelerated forgiveness timelines represent a substantial benefit for borrowers, particularly those who have been diligently making payments for years but still see a distant forgiveness horizon. It’s a recognition that smaller debts, while less daunting individually, can still accumulate and hinder financial progress. By providing a clearer and faster path to debt relief, the Student Loan Repayment 2026 changes aim to reduce the psychological and financial burden of student loans, allowing individuals to focus on other life goals like homeownership, starting a family, or saving for retirement. It’s crucial for borrowers to track their payment history and understand how these new rules might apply to their specific situation.
Key Change 3: Enhanced Benefits for Specific Borrower Groups
The third major pillar of the Student Loan Repayment 2026 reforms is the introduction of enhanced benefits tailored to specific borrower groups. While the streamlined IDR plans and accelerated forgiveness timelines offer broad relief, these targeted provisions aim to address unique challenges faced by certain populations.
What to Expect:
- Support for Low-Income Borrowers: Beyond the general adjustments to discretionary income calculations, there may be specific provisions designed to offer even greater relief to the lowest-income borrowers. This could include a ‘zero-dollar payment’ threshold that is more generous than current standards, ensuring that those earning below a certain income level have no monthly payment requirement without accruing additional interest. This is a critical safety net, preventing default and providing financial stability for those who need it most. The aim is to ensure that federal student loan payments do not become a barrier to meeting basic living expenses.
- Protection Against Interest Capitalization: Interest capitalization occurs when unpaid interest is added to your loan’s principal balance, leading to interest accruing on a larger amount. This can significantly increase the total cost of your loan over time. The Student Loan Repayment 2026 changes are expected to include provisions that limit or eliminate interest capitalization in certain scenarios, such as when a borrower moves from one repayment plan to another or during periods of negative amortization (when your payment isn’t enough to cover the accruing interest). This protection can save borrowers thousands of dollars over the life of their loans and prevent debt from spiraling out of control.
- Expanded Eligibility for Automatic Enrollment: While not a direct benefit, the potential for expanded automatic enrollment into the most beneficial IDR plan, particularly for borrowers who are struggling or at risk of default, is a significant enhancement. This proactive approach would reduce the burden on borrowers to navigate complex application processes and ensure they are receiving the relief they qualify for. This could apply to borrowers whose income falls below a certain threshold or those who are entering repayment for the first time.
These enhanced benefits underscore a commitment to making the federal student loan system more equitable and responsive to the diverse financial situations of borrowers. By targeting relief to those who need it most and by preventing common pitfalls like interest capitalization, the Student Loan Repayment 2026 framework aims to create a more sustainable and supportive environment for managing student debt. It’s important for all borrowers to understand if they fall into one of these specific groups to fully leverage the new protections and benefits available to them.
Impact on Your Budget: Preparing for the Changes
The impending changes to Student Loan Repayment 2026 will undoubtedly have an impact on your personal budget. While many of these changes are designed to be beneficial, proactive planning is essential to maximize their positive effects and mitigate any potential challenges. Here’s how to prepare:
1. Review Your Current Loan Status
Start by gathering all documentation related to your federal student loans. Log in to StudentAid.gov to view your loan types, current balances, interest rates, and your current repayment plan. Understand how much you owe and under what terms. This foundational knowledge is crucial for assessing how the new Student Loan Repayment 2026 rules will apply to your specific situation.
2. Understand Your Income and Expenses
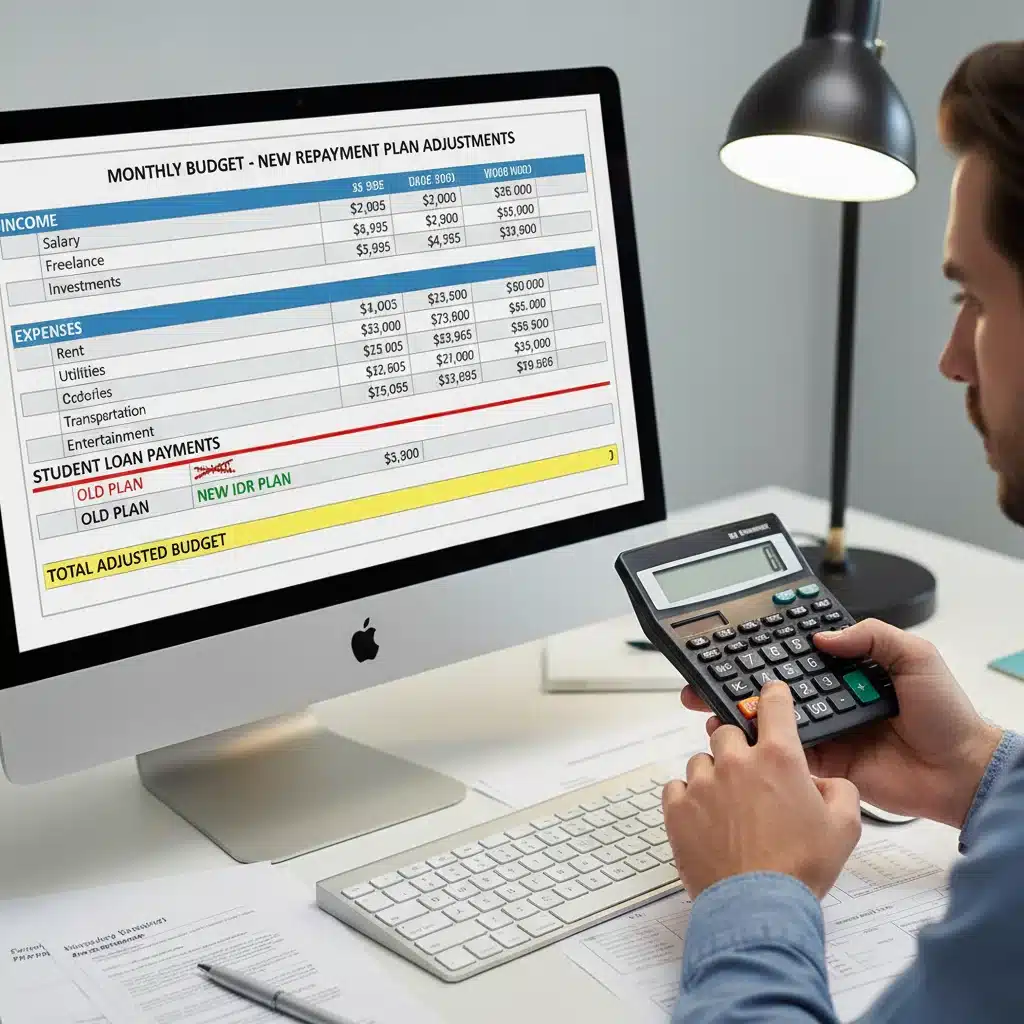
Create a detailed budget that outlines your monthly income and all expenses. This will help you understand your discretionary income, which is a key factor in IDR plans. Knowing your financial picture will enable you to project how lower monthly payments or accelerated forgiveness timelines might free up funds or adjust your overall financial strategy. Consider using budgeting apps or spreadsheets to track your spending accurately.
3. Stay Informed About Official Announcements
The exact implementation details of the Student Loan Repayment 2026 changes are still being finalized and will be communicated by the Department of Education. Subscribe to updates from StudentAid.gov, follow reputable financial news sources, and regularly check your loan servicer’s communications. Do not rely on rumors or unofficial information. Accurate and timely information will be your best asset in adapting to the new system.
4. Model Potential Scenarios
Once more definitive rules are announced, use online calculators (which will likely be updated by StudentAid.gov) to model how the new IDR calculations and forgiveness timelines would affect your loans. Compare your current monthly payment with potential new payments under the streamlined IDR plan. Estimate how much sooner you might achieve forgiveness. This exercise will provide a clear picture of your financial future under the new Student Loan Repayment 2026 framework.
5. Adjust Your Financial Strategy
If your monthly payments decrease, consider how you will use the extra funds. Options include: increasing savings, paying down other higher-interest debt, investing, or making additional payments to your student loans (if your goal is to pay them off faster than the forgiveness timeline). If you anticipate accelerated forgiveness, you might adjust your long-term financial goals accordingly. Conversely, if there are any unexpected adverse impacts (though the goal is generally positive), prepare to adjust your budget to accommodate them. This proactive adjustment is key to leveraging the changes in Student Loan Repayment 2026 to your advantage.
6. Contact Your Loan Servicer (When Appropriate)
Once the new rules are in effect, or if you have specific questions, contact your loan servicer. They will be able to provide personalized guidance on how to enroll in the new plans or understand the impact on your existing loans. Be prepared with your loan information and specific questions. Remember, servicers are there to help you navigate these changes, but it’s always best to be informed yourself first.
Long-Term Implications of Student Loan Repayment 2026
The changes coming to Student Loan Repayment 2026 are not just about short-term relief; they carry significant long-term implications for individual borrowers and the broader economy. These reforms aim to create a more sustainable and equitable system for managing higher education debt, which could have ripple effects across various sectors.
For Borrowers:
- Reduced Financial Stress: Lower monthly payments and clearer paths to forgiveness can significantly reduce the chronic financial stress associated with student debt. This can improve mental health and overall well-being for millions.
- Increased Financial Mobility: With less debt burden, borrowers may have more flexibility to pursue career paths that are personally fulfilling but perhaps lower paying, start businesses, purchase homes, or save for retirement. This can unlock economic potential that was previously constrained by student loan obligations. The ability to save for a down payment on a home, for instance, could become a reality much sooner for many.
- Improved Credit Scores: More manageable payments mean fewer defaults and delinquencies, which can lead to improved credit scores for borrowers. A better credit score opens doors to better interest rates on mortgages, car loans, and other forms of credit, further enhancing financial stability.
For the Economy:
- Stimulated Consumer Spending: When borrowers have more disposable income due to lower student loan payments, they are more likely to spend it on goods and services, stimulating local and national economies. This increased consumer demand can support businesses and create jobs.
- Boost to Homeownership Rates: Student loan debt has often been cited as a major barrier to homeownership for younger generations. By alleviating this burden, the Student Loan Repayment 2026 changes could lead to an increase in first-time homebuyers, positively impacting the housing market and related industries.
- Support for Public Service: Accelerated forgiveness for certain groups, particularly those in public service, could incentivize more individuals to pursue careers that benefit society but often come with lower salaries. This strengthens essential sectors like education, healthcare, and government.
While the full extent of these long-term implications will unfold over time, the intent behind the Student Loan Repayment 2026 reforms is clear: to create a student loan system that supports educational attainment without crippling future financial prospects. This shift represents a significant policy adjustment that acknowledges the growing burden of student debt and seeks to provide meaningful, lasting relief to those affected. Staying informed and strategically planning for these changes will be key to harnessing their benefits.
Conclusion: Navigating Your Student Loan Future
The upcoming changes to federal Student Loan Repayment 2026 represent a pivotal moment for millions of borrowers. With streamlined IDR plans, accelerated paths to loan forgiveness, and enhanced benefits for specific groups, the landscape of student debt management is set to become more manageable and equitable. These reforms are a testament to ongoing efforts to address the challenges posed by rising education costs and the resulting debt burden.
However, the benefits of these changes won’t automatically materialize. Borrowers must take proactive steps to understand, adapt, and leverage the new rules. This includes staying informed through official channels, reviewing personal financial situations, modeling potential outcomes, and adjusting budgets and long-term financial strategies accordingly. The time to start preparing is now, not when the changes are fully implemented.
By engaging with these updates, you can ensure that you are on the most advantageous repayment plan, potentially lowering your monthly payments, accelerating your journey to loan forgiveness, and ultimately achieving greater financial freedom. The Student Loan Repayment 2026 changes offer a fresh start and a renewed sense of hope for many. Embrace this opportunity to take control of your student loan debt and build a more secure financial future.